On November 5, 2026, the IRS released Revenue Procedure 2026-35, its annual inflation adjustments for tax year 2027. It covers almost 70 provisions. Most get a quick headline about the standard deduction, but several of the new numbers decide how much real estate investors keep: how much rental loss you can use, whether you get the full qualified business income deduction, and what rate applies when you sell.
Here’s what changed and how to plan around it.
What changed
The adjustments generally apply to tax years beginning in 2027, which means returns filed in 2028. The numbers that matter most to investors:
Excess business loss limit
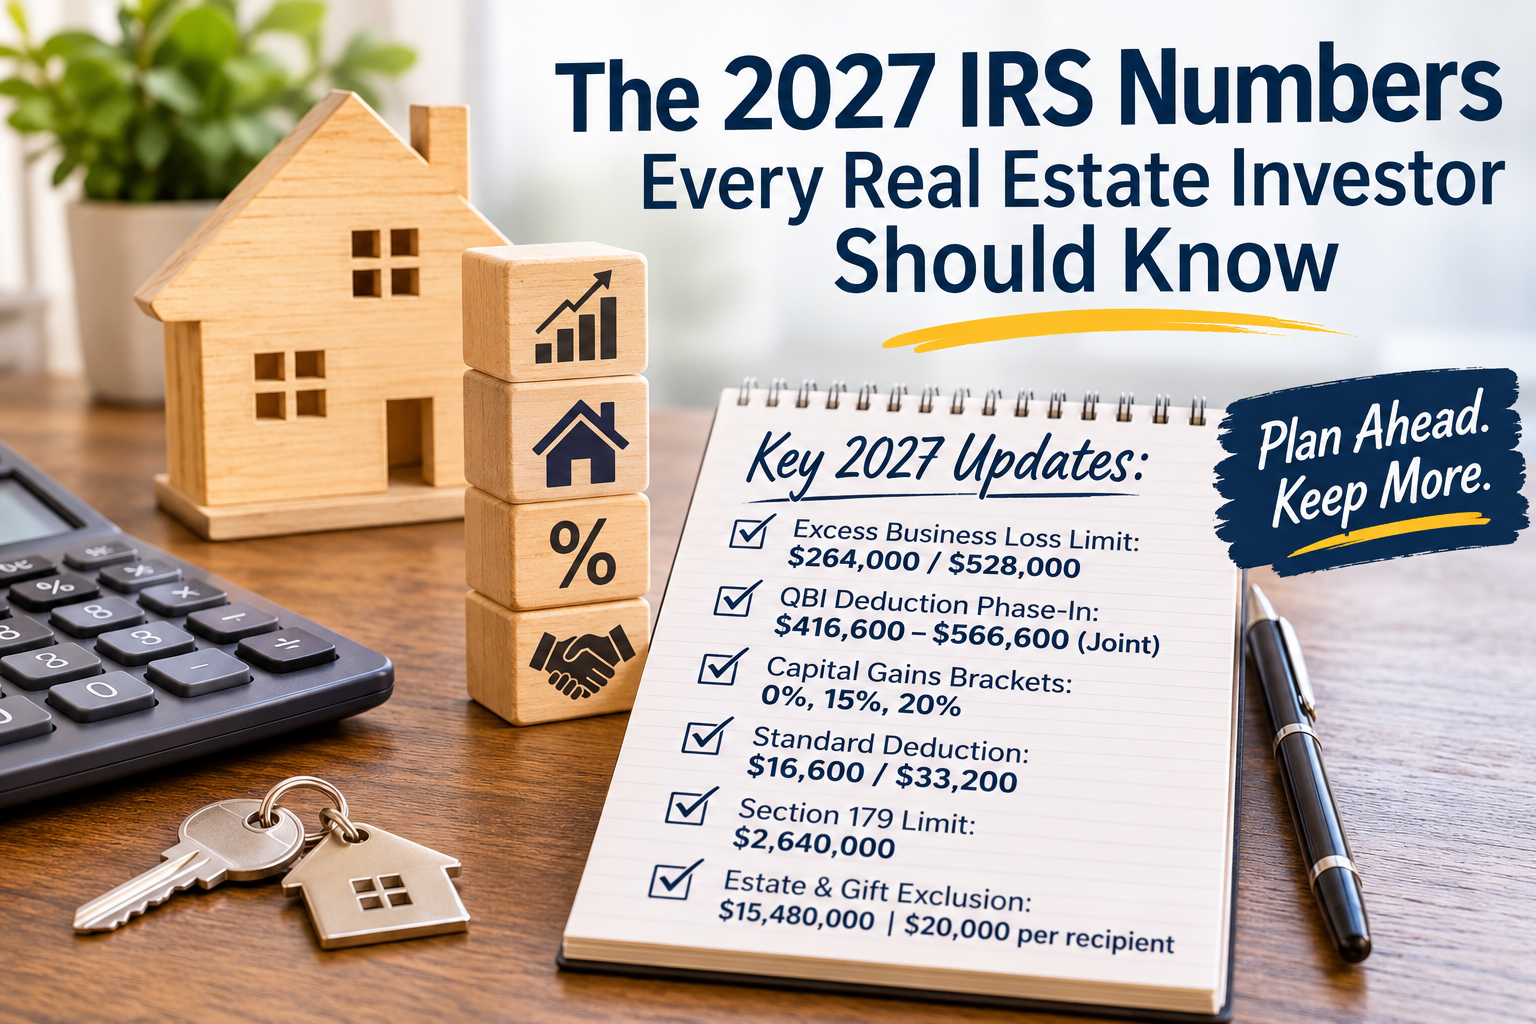
Section 461(l) caps the net business loss a noncorporate taxpayer can deduct in one year. For 2027 the limit is $264,000 for single filers and $528,000 for joint filers.
Qualified business income (Section 199A)
If your rental activity qualifies as a trade or business, the QBI deduction limitations start at $416,600 of taxable income for joint filers and phase in fully at $566,600. For most other filers, the range is $208,300 to $283,300.
Long-term capital gains brackets
The 0% rate applies up to $102,100 of taxable income for joint filers ($51,050 single). The 15% rate applies up to $633,600 joint ($563,200 single). Above that, gains face the 20% rate.
Ordinary income brackets
The 37% bracket starts above $793,650 joint and $661,375 single. The 2027 standard deduction is $33,200 joint, $16,600 single, and $24,925 head of household.
Section 179 expensing
The limit rises to $2,640,000, reduced dollar for dollar once total Section 179 property placed in service exceeds $4,230,000.
Estate and gift
The estate and lifetime gift exclusion rises to $15,480,000 per person (up from $15,000,000 in 2026). The annual gift exclusion rises to $20,000 per recipient (up from $19,000).
How the excess business loss limit hits STR investors
This is the number short-term rental investors should watch most closely.
A common strategy pairs a short-term rental with a cost segregation study and bonus depreciation. If the average guest stay is seven days or less, the property generally isn’t treated as a “rental activity” under the passive activity rules. If you also materially participate, the loss can be nonpassive and potentially offset W-2 or other income.
But nonpassive doesn’t mean unlimited. Section 461(l) then caps the net business loss you can deduct in a single year. Under the statute, the disallowed excess becomes a net operating loss carryforward to future years.
Illustrative example (hypothetical numbers)
A married couple files jointly in 2027. They buy a short-term rental, materially participate, and a cost segregation study plus bonus depreciation produces a $700,000 net loss from the property. They have no other business income or losses.
Net business loss: $700,000
2027 excess business loss limit (joint): $528,000
Loss usable against other income in 2027: $528,000
Excess carried forward as an NOL: $172,000
The $172,000 isn’t lost, but it won’t reduce 2027 taxes. That timing difference matters for cash flow planning, especially if you’re counting on a refund to fund your next deal.
Who this affects
STR investors using the short-term rental loophole with large first-year depreciation
High earners near the QBI thresholds, where a few thousand dollars of income can shrink the deduction
Investors planning a sale, who may be able to time gains into a lower bracket
Investors with larger portfolios thinking about transferring property to the next generation
What this means for you: action steps
Size your 2027 loss before you commission a cost seg study. If your projected loss far exceeds $528,000 (joint), talk with your CPA about timing acquisitions or spreading deductions across years.
Project your taxable income against the QBI range. If you’re close to $416,600 (joint), retirement contributions or deduction timing may help keep more of the deduction.
Plan sales around the gain brackets. In a lower-income year, some gain may fall in the 0% or 15% bracket. Depreciation recapture follows its own rules, so model both.
Use the $20,000 annual exclusion. Gifting partial interests in LLCs that hold property is one way families move value over time. Valuation and documentation matter here.
Keep material participation records. None of the STR loss planning works without contemporaneous logs of your hours.
Common mistakes and misconceptions
“Nonpassive means I can deduct all of it.” Not in one year. The excess business loss limit applies after the passive rules.
“The 2027 numbers apply to my 2026 return.” They don’t. Rev. Proc. 2026-35 covers tax years beginning in 2027. Your 2026 return uses the 2026 figures.
“Section 179 is the same as bonus depreciation.” They’re different provisions with different eligibility rules, and Section 179 has more limits for residential rental property. Your CPA can tell you which applies to each asset.
“The estate exemption is so high, I don’t need to plan.” Higher exemptions help, but basis, entity structure, and state rules still affect what heirs receive.
The bottom line
The 2027 numbers are mostly modest inflation bumps, but for investors with large depreciation, rising income, or a planned sale, they set the boundaries of what’s possible. The best time to plan around them is before you buy, before you sell, and before you order a cost seg study.
Ready to map your 2027 strategy? Schedule a consultation with Cornerstone CPA. We work exclusively with real estate investors and can help you model losses, QBI, and sale timing before year end.
This post is general educational information, not tax advice for any individual situation. Tax outcomes depend on your specific facts. Consult a qualified tax professional before acting.
Sources